Campaign 06 Reconciling reports
€414.78 in ad spend: how do you check unreported results?
When a screenshot shows spend but dashes for outcomes, the useful next step is a matching export. Reconcile what the interface and report actually cover before deciding whether a targeting problem exists. A missing value, a reported zero and a positive value lead to different decisions.
In 30 seconds
Reconcile scope, cost and outcome fields before judging the campaign.
- What we see
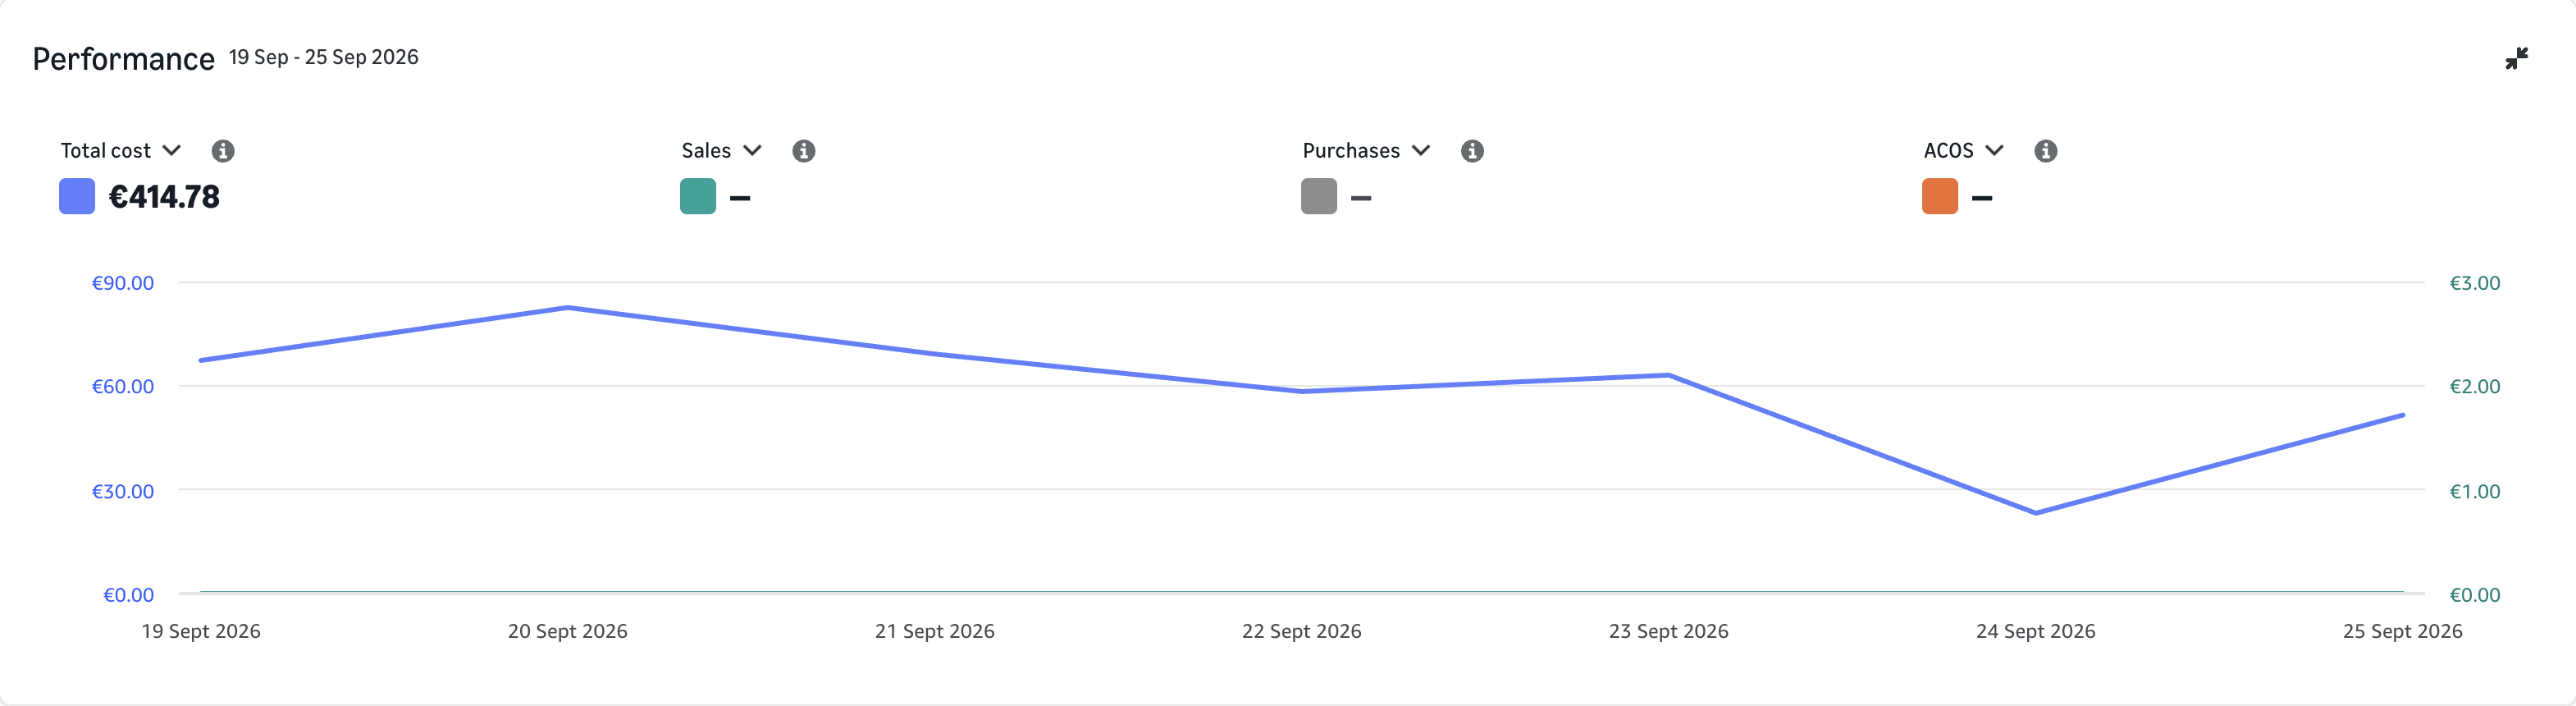
- The capture shows €414.78 in spend, while sales, purchases and ACoS are unreported.
- What to check
- Match the screenshot to an export and classify each outcome as a value, zero or still unreported.
- The next decision
- Start target-level analysis only after the return-side evidence is reconciled.
Observed campaign data from one advertising account. The steps below are proposals, not documented actions or measured improvements caused by Uptova.
Numbers & original evidence
- Ad spend
- €414.78
- Attributed ad sales
- —
- Purchases
- —
- ACoS
- —
View original capture
Swipe sideways to read. With a keyboard: focus the image region and use the left/right arrow keys.
Captured Enlarge original capture
The original interface is in English. The values and evidence have not been translated or recreated.
Our proposed action plan
Capture the reporting scope
Use the screenshot and campaign settings to produce a scope record: campaign identity, marketplace, currency, dates, capture time and visible filters. Copy €414.78 and the three dashes exactly. Leave report settings that cannot be verified marked unknown instead of completing them from another campaign.
Match the cost in an export
Obtain the relevant campaign export and record its extraction time and attribution settings. Produce a comparison of screenshot scope and exported scope, then reconcile cost with €414.78. If cost or dates differ, list the difference before importing the export’s sales figures into the interpretation.
Classify the outcome fields
Use the matched export to produce one reconciliation row each for sales, purchases and ACoS. Mark each as a reported value, reported zero or unreported, with its source. Calculate ACoS only from known cost and a positive sales denominator; keep an unexplained dash open for investigation.
Prepare the next campaign decision
Once outcomes reconcile, combine the targeting and advertised-product reports with product economics to produce a target-level review list. While they remain unavailable, produce a hold-on-expansion note and review the existing spending boundary with the owner. A precautionary restriction is different from a diagnosed zero-sales response.
The starting point
For September 19–25, Amazon displays €414.78 in spend and a dash for attributed sales, purchases and ACoS. Those three outcome fields remain unreported. A flat-looking sales line does not replace the missing summary values, and the screenshot does not explain why the dashes appear.
That leaves a specific task: verify whether another report provides the same campaign scope and complete outcomes. Attributed sales are sales credited to advertising under the report’s settings. Match marketplace, dates and attribution settings; record both extraction timestamps and check reporting maturity rather than requiring identical extraction times.
The strategic question
The distinction is practical. A reported positive value can support cost-to-sales calculations. A confirmed zero-sales value means the ratio has no sales denominator. An unreported value means the evidence is not yet available. Turning the third state into the second creates a conclusion that the report never supplied.
Use a reconciliation sheet rather than debating possible causes from the image. Record a mismatch in scope or cost first, then investigate outcomes. This produces a concrete list of what is known and what needs checking, while keeping the separate decision about acceptable ongoing spend with the seller.
How we would judge the test
The first deliverable is a reconciled report, not a performance improvement. Check whether campaign identity and cost agree, whether sales and purchases now have a supported state, and whether any remaining difference has a named follow-up. Preserve both original and later report timestamps.
If the seller then approves a targeting test, establish its baseline from the reconciled evidence and record the change separately. A newly visible sales value may reflect better reporting rather than newly created demand. Keep the reporting correction and advertising review as two distinct events.
Prepare a credible before/after
For a future test: use matching windows and reporting settings, and document price, stock and listing changes.
- 01 · Preserve the baseline
- Keep the original €414.78 and the three unreported outcome fields, alongside the screenshot’s verified scope and capture time.
- 02 · Document one change
- Document the export reconciliation first, recording a reporting correction separately from any later approved targeting adjustment.
- 03 · Measure on equal terms
- Use verified, comparable outcome fields for a later performance review; a newly reported number is not an uplift from an unknown baseline.
When to act — and when to wait
Hold expansion while sales and purchase evidence is unresolved; once scope and cost reconcile, use the verified outcome state and product economics to choose the next target-level review.
Before approving a change
- Screenshot scope recorded
- Export cost reconciled before reading outcomes
- Value, zero and unreported kept separate
- Reporting recovery separated from campaign changes
The central lesson
The immediate gain is a trustworthy starting point: the same campaign, the same cost and clearly classified outcomes.
Evidence, methodology and further reading
The cause of the unreported totals is not documented. A flat chart line does not resolve that discrepancy.
How to read these case studies
- The high-resolution originals were captured directly in an authenticated Amazon Ads session on October 21, 2026. Every capture shows exactly one campaign in Germany. The first ten analyses cover September 19–25; five additional cases also compare September 12–18, 2026. Both weeks contain the same weekdays.
- These campaigns are a deliberately selected sample from one advertising account, not a representative average. Data is not combined across sellers. Account names, campaign names and IDs have been removed by cropping; numbers, chart lines, scales and dates are unchanged.
- ACoS = ad spend ÷ attributed ad sales. The period ratio uses period totals, not the average of daily percentages. Attributed ad sales are neither total revenue nor profit; margins, returns, taxes and organic revenue are absent from these captures.
- The five before-and-after comparisons show observed time windows, not a controlled experiment or a documented Uptova intervention. Review ideas are recommendations, not documented interventions. Lower ACoS can accompany fewer purchases; a week establishes neither durable profitability nor incremental sales.
- The captures were retaken without the pointer after the chart animation finished, then cropped only. No chart was generatively retouched. Cost, sales and ACoS use separate scales, not a shared value scale; gaps in the ACoS line can represent days without a defined daily ratio.
- Reports can use different levels of detail and attribution windows. Queries, products and placements remain separate views unless their relationship is verified. The purchased-product report discussed in these review plans shows purchases of other products but no ad cost; it cannot supply ACoS per purchased product.