Campaign 15 Sponsored Brands: objective before test
15.93% ACoS: does this Sponsored Brands campaign meet its goal?
Sponsored Brands ACoS improves while advertising cost per reported purchase rises slightly. This campaign’s name suggests video, but the creative format still needs verification. First distinguish the arithmetic from the objective: a sales review and an awareness review need different evidence.
In 30 seconds
A better sales ratio is not automatically cheaper acquisition, wider reach or a reason to change the creative.
- What we see
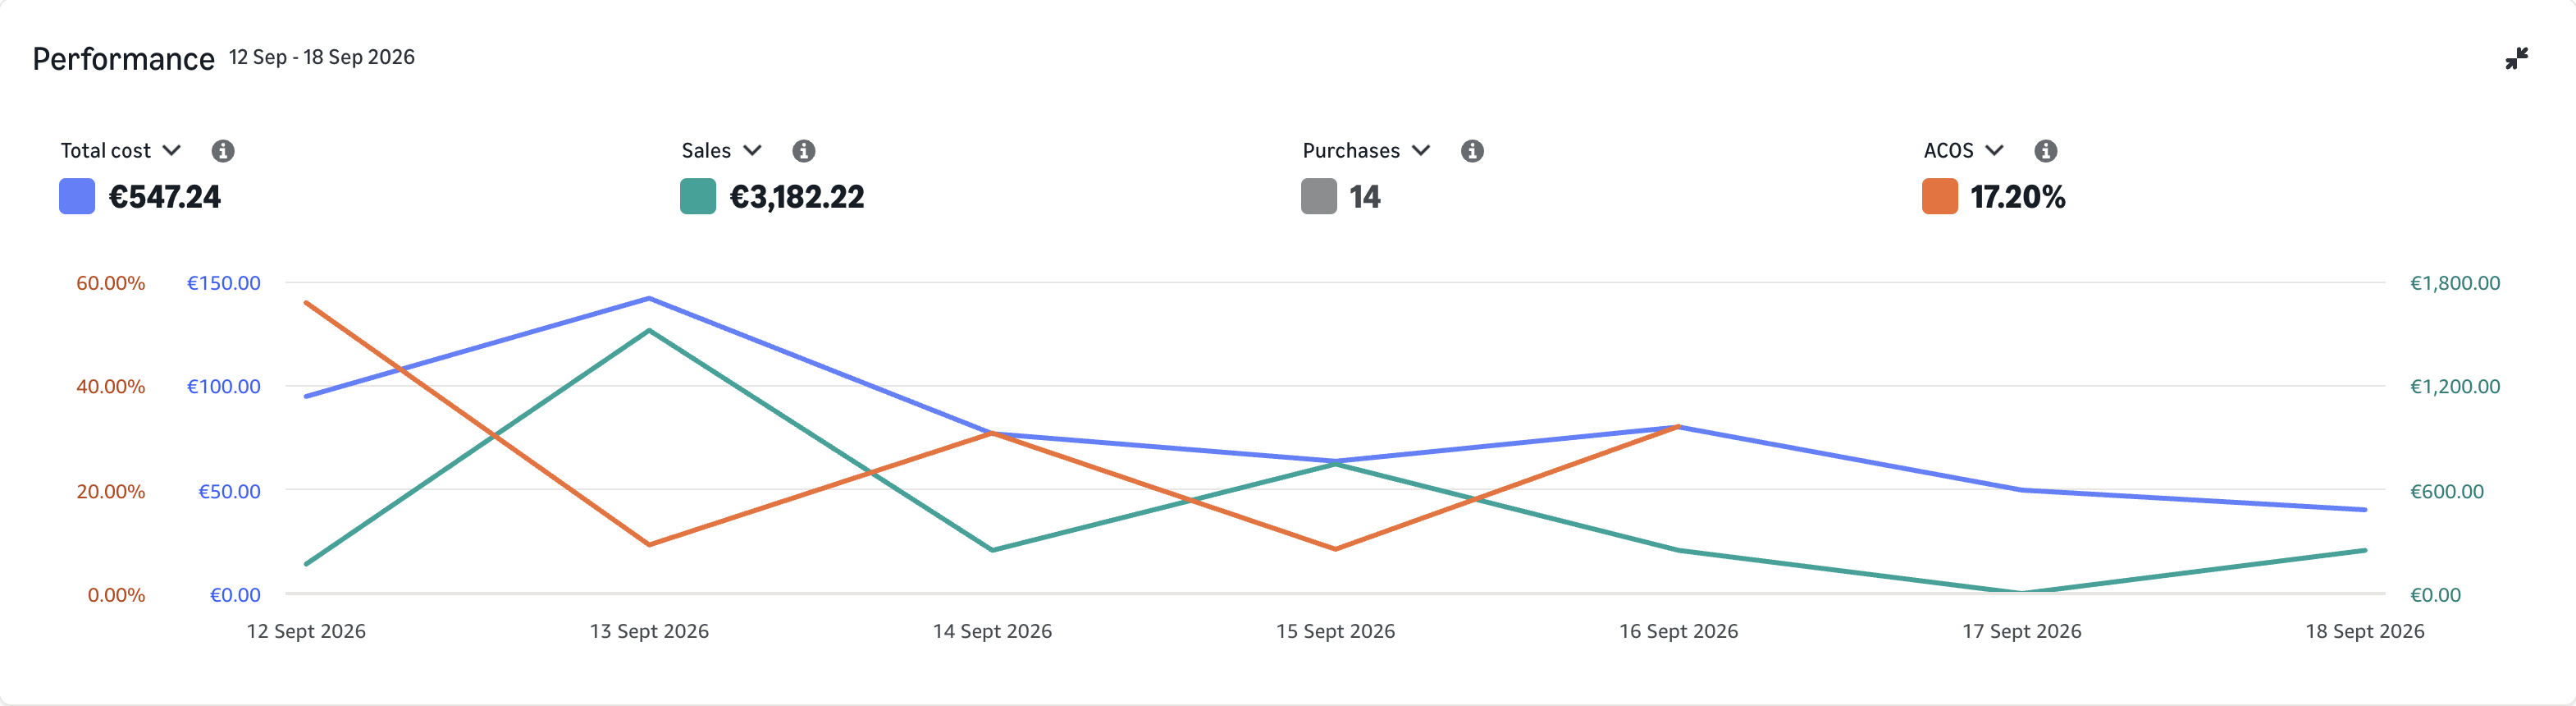
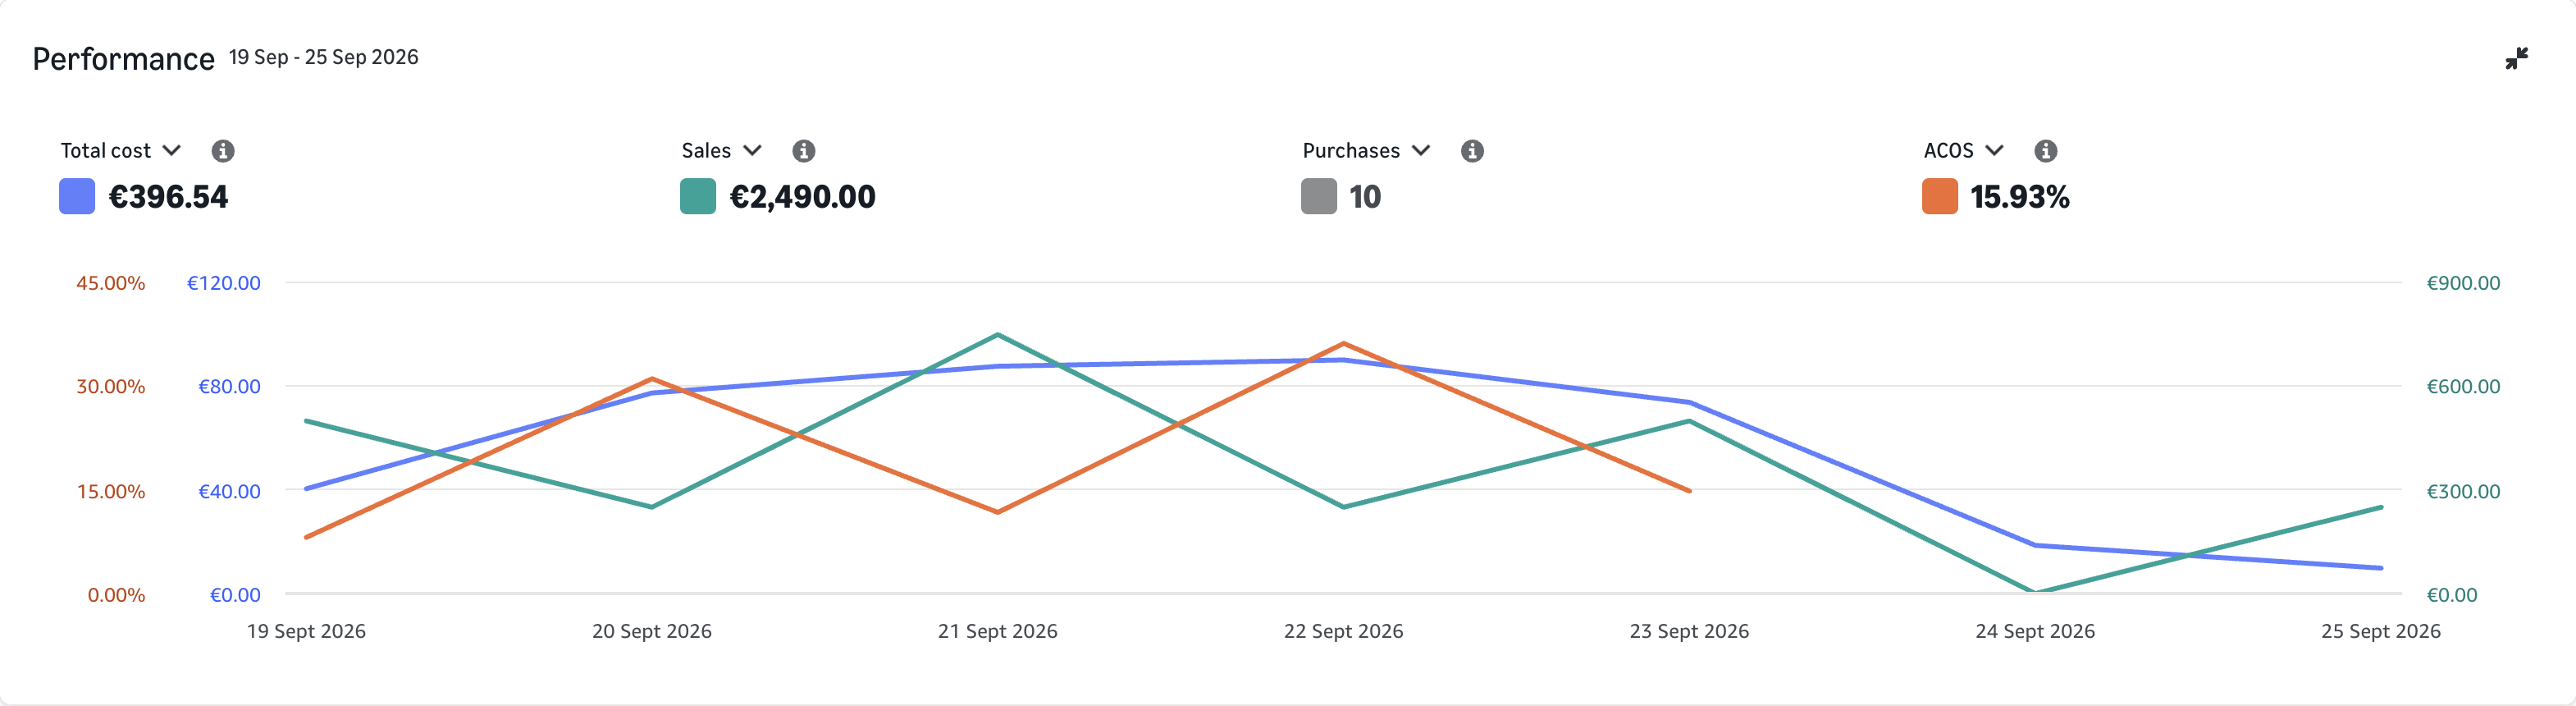
- Spend falls from €547.24 to €396.54 and ACoS from 17.20% to 15.93%. Purchases decline from fourteen to ten.
- What to check
- Verify the actual format and objective, then separate cost per reported purchase from attributed sales per reported purchase.
- The next decision
- Do not change creative or budget from these totals alone. Revisit a specific hypothesis once its objective, weakness and available measurement are documented.
Observed campaign data from one advertising account. The steps below are proposals, not documented actions or measured improvements caused by Uptova.
Numbers & original evidence
Both weeks at a glance
Sep 12–18, 2026Sep 19–25, 2026
Ad spend
- Before
- €547.24
- After
- €396.54
- Change
- -27.54%
Attributed ad sales
- Before
- €3,182.22
- After
- €2,490.00
- Change
- -21.75%
Purchases
- Before
- 14
- After
- 10
- Change
- -28.57%
ACoS
- Before
- 17.20%
- After
- 15.93%
- Change
- -1.27 percentage points
Ad cost per purchase
- Before
- €39.09
- After
- €39.65
- Change
- +1.45%
Attributed ad sales per purchase
- Before
- €227.30
- After
- €249.00
- Change
- +9.55%
Calculated from period totals. Purchases are ad-attributed purchases, not unique customers. Sales per purchase is neither total basket value nor margin.
View both original captures
The original interface is in English. The values and evidence have not been translated or recreated.
Before · earlier period
Sep 12–18, 2026
Swipe sideways to read. With a keyboard: focus the image region and use the left/right arrow keys.
Captured Open the earlier week’s original
After · later period
Sep 19–25, 2026
Swipe sideways to read. With a keyboard: focus the image region and use the left/right arrow keys.
Captured Open the later week’s original
Chart scales can differ; compare the numbers, not the height of the lines.
Our proposed action plan
Write a format-and-objective brief
Open the campaign and actual creative. Record the format, destination and intended objective: attributed sales or a separately measured awareness goal. List the metrics actually available for that format. Deliver a one-page brief, keeping unsupported video or new-customer measures open rather than selecting a metric from the campaign name.
Explain the sales ratio before judging it
Reconcile the two reports under matching date, currency and attribution rules. Show purchase count, cost per reported purchase and attributed sales per reported purchase together. For a sales objective, add available branded and generic query groups and product economics. Deliver a comparison that distinguishes ratio improvement from acquisition cost.
Inspect one measurable friction point
Review the actual creative, destination, advertised products, price and availability together. Describe one observable issue and the evidence needed to evaluate it. If none is established, record that finding rather than proposing a redesign. Keep separate query, product and format reports within their verified coverage.
Choose a test that matches the objective
Only for a supported issue, name one change, starting state, intended metric, maximum cost and review date. Keep other changes separate. A sales test needs product economics; an awareness test needs an available awareness measure. Without suitable evidence, retain observation rather than treating the lower ACoS as approval.
The starting point
September 12–18 records €547.24 in spend, €3,182.22 in attributed sales and fourteen purchases. September 19–25 records €396.54, €2,490 and ten purchases. Both original captures concern the same German Sponsored Brands campaign, whose name points to video. The actual creative format needs a separate check. The campaign was paused when reviewed; that does not establish when an earlier pause occurred.
Cost per reported purchase rises from €39.09 to €39.65, or 1.4%. Attributed sales per reported purchase rises from €227.30 to €249, or 9.5%. These divisions of the period totals explain how ACoS can fall from 17.20% to 15.93%. They are not transaction-level basket values, margin or evidence about new customers.
The strategic question
The higher attributed sales per purchase outweighs the slight increase in purchase cost in this aggregate calculation. The cause remains open. For a sales objective, inspect queries and product economics; for awareness, first identify the relevant available format metrics. Neither video views nor new-to-brand share is shown in these captures.
Match reporting and attribution settings across the periods, recording campaign changes separately. Then verify the actual ad and destination page. A product detail page and a Store can present different review questions. Neither the campaign name nor the total ACoS proves a creative defect, a destination problem or a brand effect.
How we would judge the test
After an approved sales test, compare purchase count and both ratio components within the same campaign scope. Evaluate the result against the product allowance, not the headline percentage alone. An awareness test must use its own predefined measurement rather than borrowing a sales conclusion.
Use complete, equal-length windows and record price, stock and listing changes. Check reporting definitions before comparing ad types. The current paused status has no verified historical start date; do not place it retrospectively between the weeks or treat it as the cause of the observed change.
What this weekly comparison establishes
Keep the original periods and the evidence needed for a follow-up test documented separately.
- 01 · Preserve the baseline
- Earlier original capture: €547.24 in spend, €3,182.22 in attributed sales, fourteen purchases and 17.20% ACoS.
- 02 · Document one change
- No intervention between the weeks is established. The current paused status is not interpreted retrospectively as the cause.
- 03 · Measure on equal terms
- Later original capture: €396.54 in spend, €2,490 in attributed sales, ten purchases and 15.93% ACoS.
When to act — and when to wait
For now, do not infer a creative change or budget increase from ACoS. Revisit one hypothesis after verifying the actual format, objective and measurable weakness. Review an approved test on its agreed metric and date, stopping earlier if its spending limit or product-availability condition fails.
Before approving a change
- Actual format and objective documented
- Both sales-ratio components calculated
- One observable issue and suitable metric identified
- Test limit and review date agreed
The central lesson
Choose the objective before the test: this lower ACoS does not mean a lower cost per reported purchase.
Evidence, methodology and further reading
Views, new-to-brand share and brand effects are not recorded. The time comparison does not establish an Uptova effect.
How to read these case studies
- The high-resolution originals were captured directly in an authenticated Amazon Ads session on October 21, 2026. Every capture shows exactly one campaign in Germany. The first ten analyses cover September 19–25; five additional cases also compare September 12–18, 2026. Both weeks contain the same weekdays.
- These campaigns are a deliberately selected sample from one advertising account, not a representative average. Data is not combined across sellers. Account names, campaign names and IDs have been removed by cropping; numbers, chart lines, scales and dates are unchanged.
- ACoS = ad spend ÷ attributed ad sales. The period ratio uses period totals, not the average of daily percentages. Attributed ad sales are neither total revenue nor profit; margins, returns, taxes and organic revenue are absent from these captures.
- The five before-and-after comparisons show observed time windows, not a controlled experiment or a documented Uptova intervention. Review ideas are recommendations, not documented interventions. Lower ACoS can accompany fewer purchases; a week establishes neither durable profitability nor incremental sales.
- The captures were retaken without the pointer after the chart animation finished, then cropped only. No chart was generatively retouched. Cost, sales and ACoS use separate scales, not a shared value scale; gaps in the ACoS line can represent days without a defined daily ratio.
- Reports can use different levels of detail and attribution windows. Queries, products and placements remain separate views unless their relationship is verified. The purchased-product report discussed in these review plans shows purchases of other products but no ad cost; it cannot supply ACoS per purchased product.